
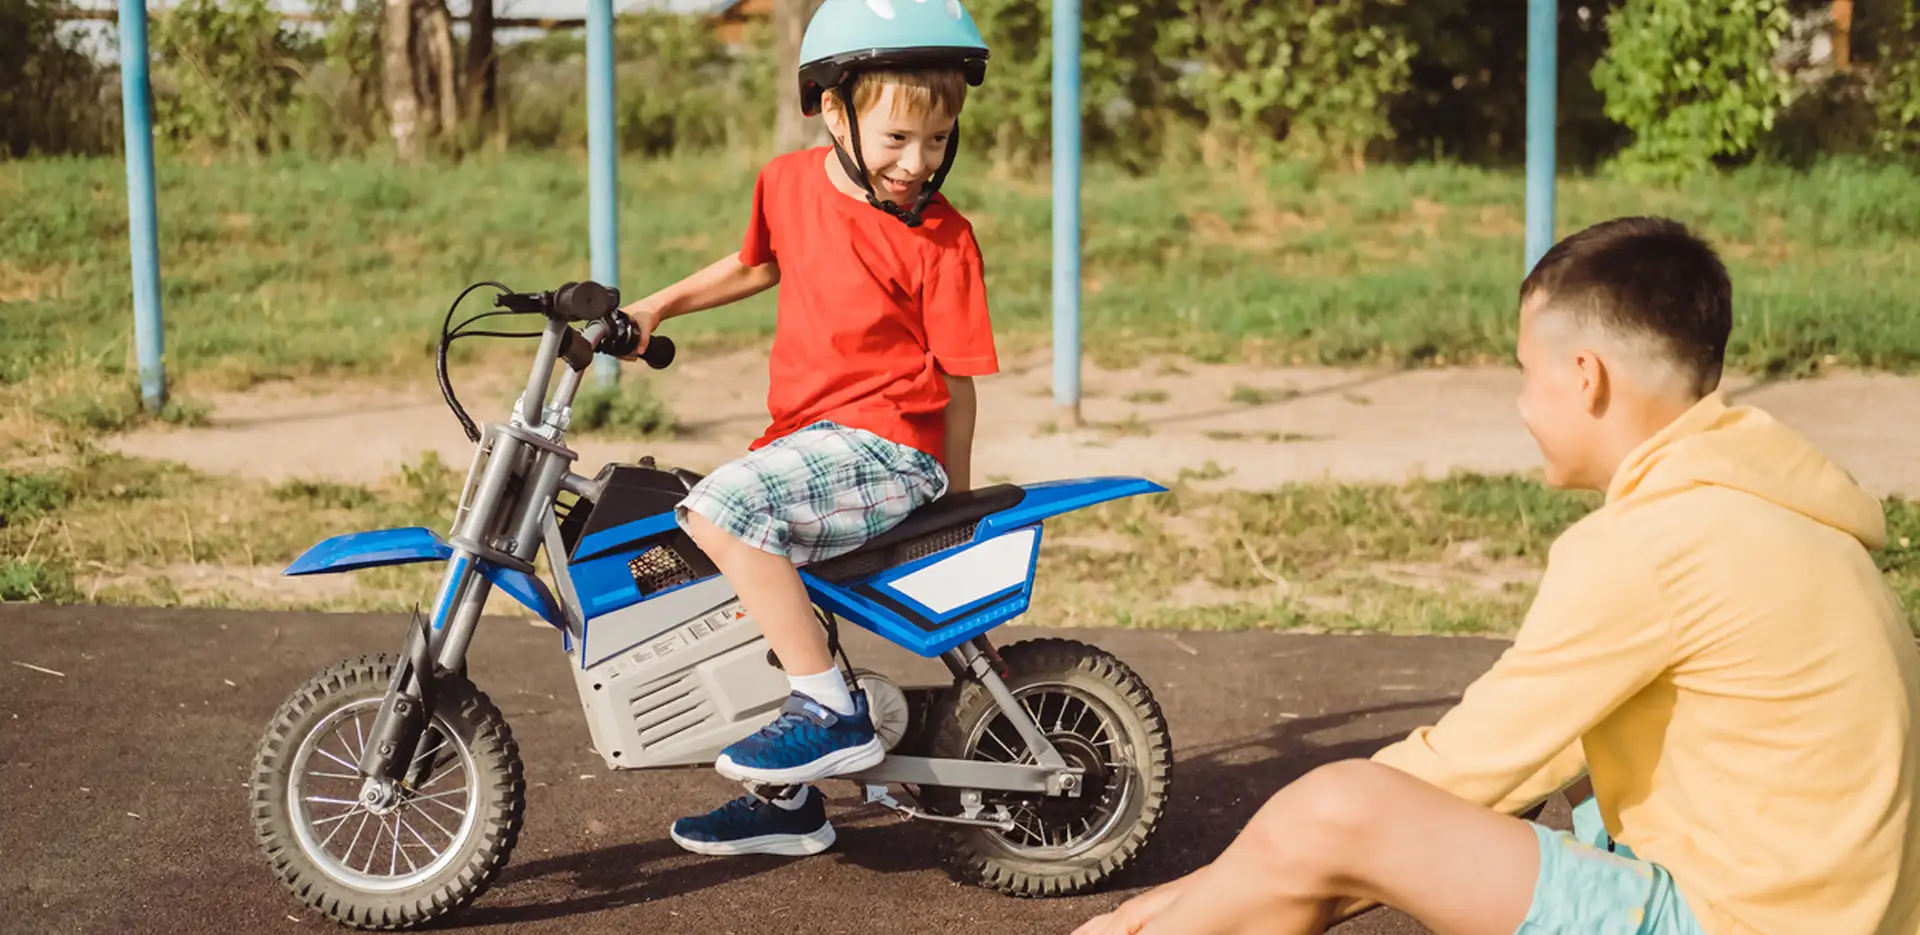
The popularity of e-bikes has exploded in recent years. U.S. e-bike sales climbed from about 50,000 units in 2018 to more than 527,000 in 2022, making them a common sight in neighborhoods, parks and on local streets.
Injuries have increased just as dramatically. According to the American College of Surgeons, e-bike injuries have surged more than 300% since 2019. A study published in JAMA Surgery found that nationwide e-bike-related injuries increased from roughly 1,600 in 2018 to 23,000 in 2022.
E-bikes pose a growing risk to families, particularly when ridden by children or teenagers. A young rider can be severely injured or killed in a crash. If the rider causes an accident, their parents may be held liable.
A recent California case illustrates how serious the consequences can become. Prosecutors allege that a 14-year-old riding a high-powered electric motorbike in Orange County struck an 81-year-old pedestrian, causing severe injuries.
Authorities also charged the boy’s mother, alleging that she had been previously warned about the dangers of allowing her son to operate the bike. While the legal outcome remains to be seen, the case shows that parents may face significant legal and financial liability when their child injures someone or damages property while riding an e-bike.
Insurance
Parents may be held liable for damages caused by their child in an e-bike or e-scooter accident in California, but the injured victim’s ability to recover compensation often depends on whether the accident is covered by the parents’ insurance.
Many homeowners and renters assume their property insurance automatically covers liability from an e-bike accident, but that may not be the case.
Standard homeowner’s or renter’s policies provide personal liability coverage for the named insureds (the parents) and additional insureds (their minor children). However, most of these policies exclude liability coverage for injuries caused by motor vehicles.
So, the question becomes: Is the e-bike a “motor vehicle” as defined by the policy? Low-speed, pedal-assist (Class 1) e-bikes are sometimes treated as regular bicycles under a homeowner’s policy, whereas throttle-equipped (Class 2) or faster (Class 3) e-bikes are more strictly classified as motorized vehicles.
Also, your auto insurance policy won’t cover liability for an e-bike accident that causes injury or damage to a third party’s property.
Even when insurance applies, a serious claim could exceed the policy’s liability limits. An umbrella policy may provide additional liability coverage beyond the limits of an underlying homeowner’s policy, depending on the circumstances and the terms of both policies.
What you can do
The best time to determine whether your family has adequate coverage is before an accident occurs. If you’ve recently purchased an e-bike for your child or are considering purchasing one, review your homeowner’s or renter’s policy with us.
We can help determine whether the e-bike qualifies for coverage, explain any limitations that may apply and discuss whether endorsements or additional liability protection make sense for your family. Some insurers will let you purchase an endorsement that extends personal liability to an e-bike.
Some companies have also started offering e-bike insurance policies, but not all of them include liability coverage. Many primarily cover theft of or damage to the bike.